
Looking for expert help with workers' compensation?
Match benefit notices to supplied payment records
How Can Virtual Legal Assistants Help with benefit notice and payment reconciliation?
Virtual legal assistants from Remote Legal Team can support payment-ledger organization by logging notices, matching supplied payment evidence, and preparing exception lists for attorney review.
Legal assistant
Remote paralegal
Intake specialist
The task and the problem
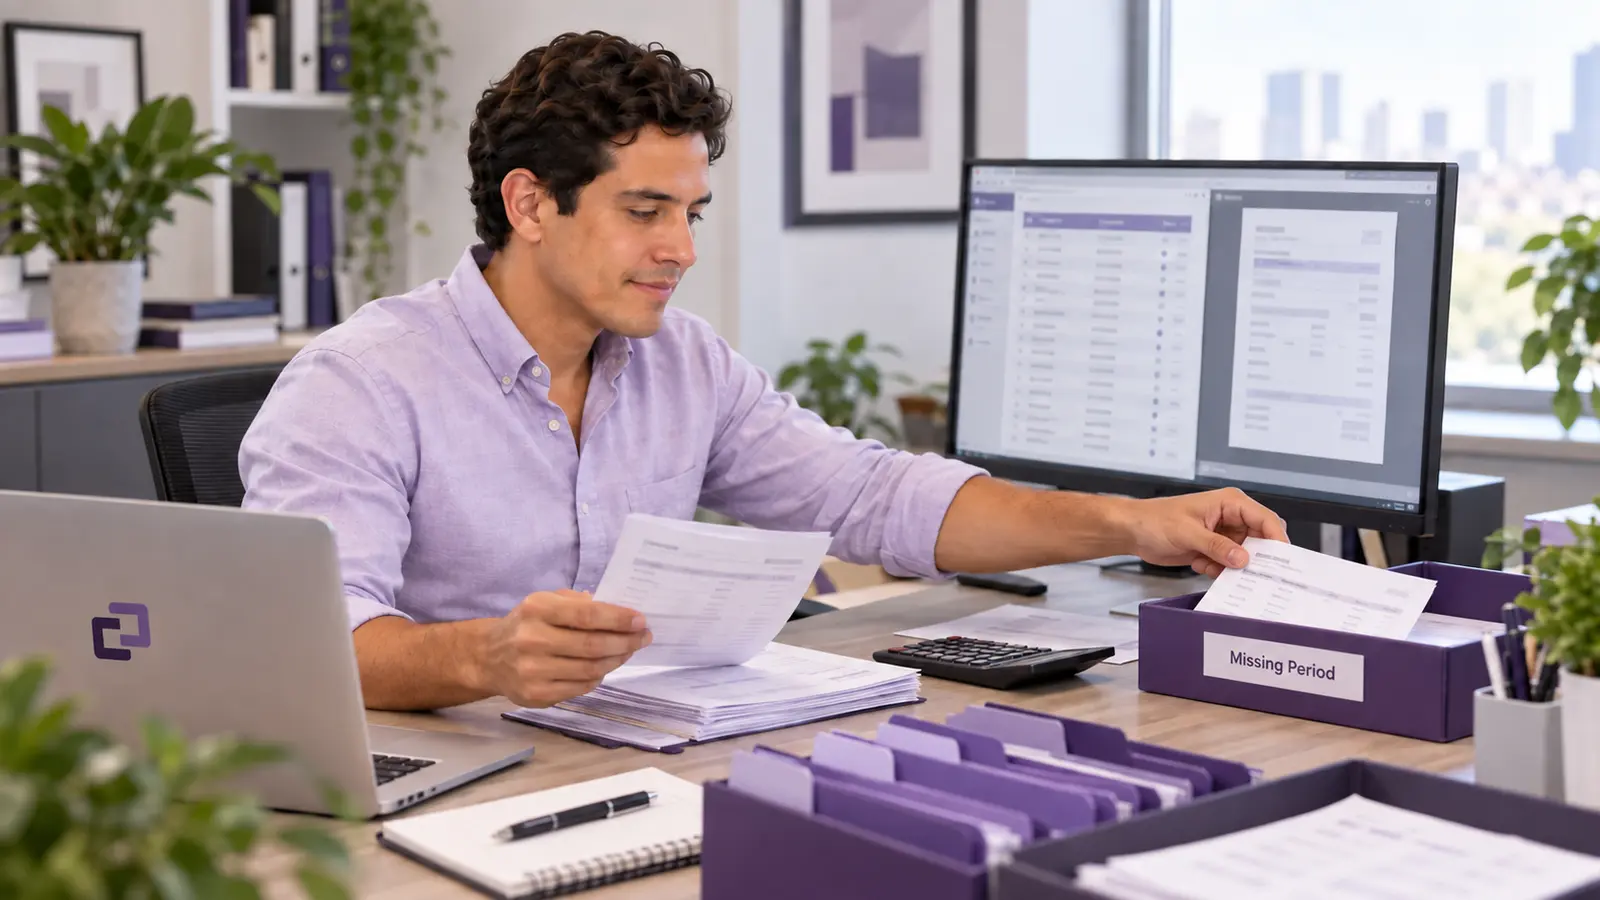
A notice can describe one benefit period while a deposit combines several payments or includes a reversal. Remote benefit notice payment reconciliation preserves the notice's wording and the payment evidence separately before proposing a match. The ledger should expose uncertainty rather than make the numbers appear reconciled through assumptions, using legal document management support to keep raw records distinct.
California DWC's employee FAQs discuss workers compensation benefits. The source supplies named-state context, not the calculation method for this illustrative ledger or a nationwide payment rule.
What the firm supplies
Counsel supplies notices, remittance details, approved payment evidence, the review period, and a reviewer. Instructions distinguish stated entitlement from confirmed payment and specify masking of financial identifiers. The assistant needs reversal and replacement notices where supplied. Counsel selects applicable benefit rules and calculations, assesses delays, and approves any inquiry. No account access or payment instruction is included.
How the work moves
| Step | Input | Assistant action | Output | Attorney review |
|---|---|---|---|---|
| 1 | Notices and payment records | Register source dates, stated periods, and identifiers | Payment source ledger | Confirm scope |
| 2 | Matching references | Link notices to payments without inferring entitlement | Notice-payment crosswalk | Resolve ambiguous allocations |
| 3 | Reversals and gaps | Preserve adjustments and flag unmatched amounts | Exception schedule | Decide legal calculation needs |
| 4 | Checked evidence | Assemble source copies and focused questions | Payment review packet | Approve dispute or inquiry |
Illustrative example
Illustrative matter PAY-G uses hypothetical figures only: notice N1 lists $600 and remittance P1 also lists $600, but their stated periods differ. No underpayment is calculated.
| Pair | Notice period | Payment period | Review issue |
|---|---|---|---|
| N1 / P1 | Period A | Period B | Amount matches; allocation unresolved |
| N2 / P2 | Period C | Period C | P2 marked reversed; replacement missing |
| N3 / none | Period D | No evidence supplied | Receipt unconfirmed |
The assistant does not count P2 as a final payment or describe N3 as unpaid without qualification. The handoff states exactly which evidence is missing.
Deliverables, missing information, and escalation
Deliver the source ledger, crosswalk, reversal register, and unresolved allocation questions. Acceptance requires preserved period labels, no double counting of reversals, and clear distinction between no payment evidence and no payment. Escalate a cessation notice or apparent urgent financial concern to counsel promptly. An outsourced Workers Compensation paralegal may maintain the ledger in a settlement administration support style workflow, but the attorney determines entitlement, penalties, offsets, and response strategy. No carrier demand, account change, or filing is sent automatically.
Systems and responsible AI use
Use a restricted ledger with raw amounts preserved and separate review-status fields. Approved extraction may copy notice data, but verify against original documents and remittance records. No confidential financial data enters unapproved AI. No autonomous benefit calculations, messages, filings, legal judgments, or legal-date calculation is permitted. ABA Model Rule 5.3 gives supervisory context.
What the firm could measure
For each monthly reconciliation cycle, measure notices with a source-supported match or explicit unresolved disposition divided by notices reviewed. Count unmatched reversals and period conflicts from the exception schedule. These proposed measures evaluate evidence organization, not benefits owed, legal timeliness, or recoverable penalties.
Practical questions
Does a missing deposit establish nonpayment?
It establishes only that the supplied evidence does not confirm receipt. Ask counsel whether remittance information or another approved source should be requested.
Can the assistant calculate the amount the carrier should have paid?
Counsel must supply the legal methodology and approved inputs. Keep raw notices and payment evidence available for that separate calculation.
What if several notices match one deposit?
Record a possible grouped payment without allocating it by guesswork. Request a remittance breakdown through the approved review route.